Strong TSP returns mask hidden risks.
Issue 01 | May
THIS MONTH IN FEDERAL BENEFITS ADVISORS
Strong TSP returns mask hidden risks. Are you protected?
Year-to-date gains look healthy on paper but volatility, elevated valuations, and sequence of return risk create a dangerous environment for federal employees within 3 years of retirement.
01 • TSP AT A GLANCE
Double-digit returns with a catch
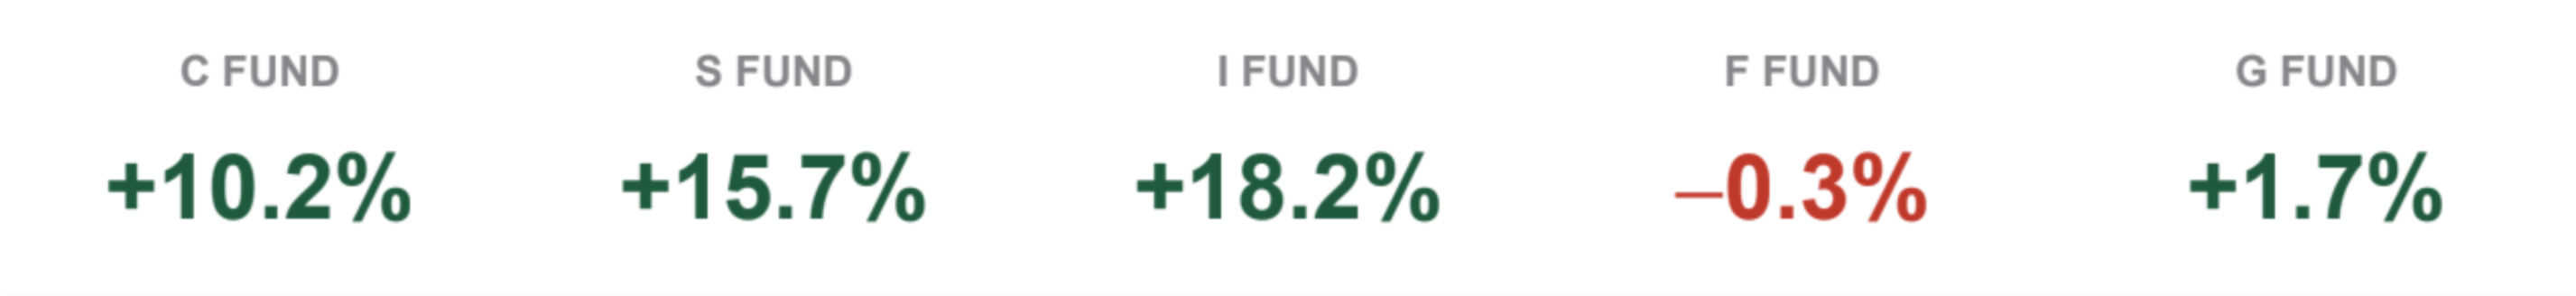
Through late May, all three TSP equity funds remain in positive territory year-to-date, led by international equities. But the path hasn't been smooth.
184,532 | -4.98% |
TSP millionaires as of the most recent FRTIB report, a new record. | C Fund's single-month drop in March 2026, a $25,000 loss on a $500K balance in 30 days. |
THE VOLATILITY BENEATH THE SURFACE
March 2026 saw the sharpest TSP drawdown in over a year. The C Fund dropped 4.98% and the S Fund fell 4.58% in just 30 days before recovering in April and May.
Here's the critical question: What if you had retired on March 1st instead of May 1st? The timing of your retirement date and when you begin taking withdrawals can create a difference of tens of thousands of dollars over a 20-year retirement.
02 • STATE OF THE MARKETS
What federal employees need to know right now
Sequence of return risk explained
Two federal employees with identical TSP balances, identical allocations, and identical long-term average returns can end up with vastly different retirement outcomes based solely on when the bad years happen.
If you experience negative returns in the first few years of retirement, when you're taking withdrawals and can no longer contribute, your portfolio may never recover, even if markets rebound later. This is called sequence of return risk, and it's the single biggest threat to federal employees within 3 years of retirement.
The March volatility is a case study: retiring March 1 versus April 1 created a 5%+ difference in starting account value. Over a 20-year retirement, that gap compounds into six figures of lost income.
The market valuation question
The S&P 500 (which the TSP C Fund tracks dollar-for-dollar) is now valued at 252% of U.S. GDP, the highest level in American history.
For context:
1929 peak: 65% of GDP
2000 dot-com peak: 170% of GDP
Today: 252% of GDP
Several prominent investors, including legendary hedge fund manager Paul Tudor Jones (who famously predicted the 1987 crash), have publicly warned that current valuations leave little room for error. Jones predicts an eventual 30-35% correction when the AI investment cycle matures, though he expects the rally to continue for another 1-2 years.
For federal employees in the C Fund, that matters. A 30% correction would erase 18 months of gains and take account balances back to late 2024 levels.
The G Fund dilemma
Many federal employees respond to market volatility by moving into the G Fund and it's easy to understand why. The G Fund never loses value and offers guaranteed returns.
But here's the problem: the G Fund is earning about 1.7% year-to-date while inflation is running at 3-4%. That means you're losing purchasing power even though your account balance is growing.
This is what financial planners call 'the safety trap'; you're protected from market losses, but you're guaranteed to lose the race against inflation.
The income gap no one talks about
Most federal employees retire with three income sources: a FERS pension, Social Security, and TSP withdrawals. Here's what many don't realize:
Your FERS pension has a cost-of-living adjustment, but it lags inflation (2% COLA vs. 3-4% inflation this year)
Your FEHB premium just jumped 12.3% which completely wipes out your COLA increase
Your TSP is either losing to inflation (G Fund) or exposed to sequence risk (C/S/I Funds)
If you retire before age 62, the FERS Supplement fills the gap until Social Security kicks in but it stops at 62 whether you claim Social Security or not
That creates an income gap that lasts from age 62 until you turn on Social Security (often age 67 for full retirement age). And if you're deferring Social Security to age 70, that gap lasts 8 years.
What you can control
You can't control whether the market corrects 30% next year or rallies another 40%. You can't control inflation or FEHB premium hikes or Congressional reconciliation bills. But you can control:
Your TSP allocation strategy; derisking in the 3 years before retirement to protect against sequence risk
Your income plan; structuring guaranteed income sources to fill the gap between the FERS Supplement ending and Social Security starting
Your timing; understanding the cost of waiting and the value of planning before you're 6 months from retirement
The federal employees who weather market volatility best aren't the ones with the highest risk tolerance. They're the ones with a plan.
QUESTIONS WORTH ASKING YOURSELF
Do you know your exact retirement income gap, down to the dollar, and how you'll fill it?
If the TSP C Fund dropped 30% the month before you retire, would your retirement plan survive?
Have you calculated whether deferring Social Security to age 70 actually makes sense given your TSP allocation and life expectancy?
Do you have a written derisking strategy for your TSP in the 3-5 years before retirement?
If the answer to any of those is 'no' or 'I think so,' the cost of waiting to get clarity could be $50,000 to $200,000 in lost lifetime income.
03 • 2027 COLA WATCH
April inflation pushes COLA estimates higher
Following April's CPI-W reading of 3.8%, the Senior Citizens League raised its preliminary 2027 Cost-of-Living Adjustment estimate to 3.9%, up from earlier projections in the 2.8% range. The official COLA is set in October based on the Q3 CPI-W average.
The COLA applies to Social Security benefits, CSRS annuities, and FERS annuities for retirees age 62 and older. FERS retirees under 62 do not receive the COLA on their basic annuity.
FERS COLA REMINDER
When the COLA exceeds 3%, FERS retirees receive the COLA minus one percentage point. A 3.9% Social Security COLA would translate to roughly a 2.9% FERS COLA for eligible retirees.
04 • FEHB 2027 PREVIEW
OPM Call Letter signals continued focus on prevention
OPM's 2027 FEHB Call Letter, issued earlier this spring, asks carriers to strengthen offerings around obesity treatment and prevention, mental health parity, and primary-care access. Carrier benefit and rate proposals were due May 31.
Final 2027 premiums and plan details typically become public in late September, ahead of Open Season (mid-November through mid-December). Enrollees should expect the usual mix of plan exits, new entrants, and benefit refinements.
WHAT TO WATCH
Premium trends, network changes in your region, and whether any 2026 carriers withdraw from FEHB. Open Season planning materials will be published in early fall.
05 • LEGISLATIVE WATCH
FERS Supplement survives again
The House reconciliation bill once again proposed eliminating the FERS Annuity Supplement for new retirees and raising employee contributions to 4.4%. Both provisions were dropped during Senate consideration, consistent with every prior attempt over the past decade.
Other federal workforce provisions still in discussion include proposals around new-hire employment classification and performance-based retention policies, but no major changes have been enacted.
STATUS
The FERS Supplement is safe. No material changes to current FERS benefits have been enacted. For current rules, OPM's Retirement Information Center remains the official reference.
06 • RIF RULES UPDATE
OPM finalizing three proposed RIF changes
OPM closed the public comment period this spring on three proposed rules affecting how Reduction-in-Force actions are conducted:
Tightening how performance ratings are distributed within agencies
Weighting performance over tenure as the primary retention factor
Shifting initial appeals of RIF actions from MSPB review to OPM administrative review
A final rule is expected later this summer. The changes, if finalized, would affect retention standing in any future RIF event.
07 • QUICK REFERENCE
Numbers worth knowing
FERS PENSION FORMULAHigh-3 × Years of Service × 1.0% (1.1% if retiring at 62+ with 20+ years) | MINIMUM RETIREMENT AGE57 for employees born in 1970 or later |
2026 TSP CONTRIBUTION LIMIT$24,500 elective deferral. Catch-up: $8,000 (age 50+); $11,250 (ages 60–63) | SOCIAL SECURITY FRA67 for those born in 1960 or later |
FEHB OPEN SEASONMid-November through mid-December (annual) | FERS SUPPLEMENT ELIGIBILITYAvailable to FERS retirees who retire before age 62 with full eligibility; ends at 62 |
SOURCES CONSULTED
FedSmith.com · TSPFolio.com · TSP Market Watch · FedWeek · Federal News Network · GovExec · OPM.gov · The Senior Citizens League · FRTIB monthly reports · Paul Tudor Jones interviews (CNBC, Yahoo Finance, April-May 2026). Data current as of May 27, 2026.
This update is for informational and educational purposes only. It does not constitute financial, tax, or legal advice and should not be relied upon for any individual planning decisions. Always consult official OPM, SSA, and TSP resources for the most current rules affecting your specific situation.
PREPARED BY JOE AND THOM GLEASON
